#339 How Physicians Keep More of What They Earn (and Build a Life Around It) ft. Peter Kim, MD, Eric Tait, MD, Austin Dean, Kim Hopkins, Corey Daharsh, and Mike Woo-Ming, MD
Episode Highlights
Now, let’s look at what we discussed in this episode:
- Keeping More, Not Just Earning More
- What Wealth Actually Means
- Finding Your Number and Making a Plan
- Tax Strategy You Can Still Use This Year
- Favorite Strategies and What to Do Before Year End
Here’s a breakdown of how this episode unfolds.
Episode Breakdown
Keeping More, Not Just Earning More
Peter opens with something he’s noticed after years of doing this. Most physicians spend far more time thinking about how to earn more than how to keep more. He believes the keeping side is where a lot of the leverage is, things like taxes, different structures, where your money sits, and what you’re building toward in the first place.
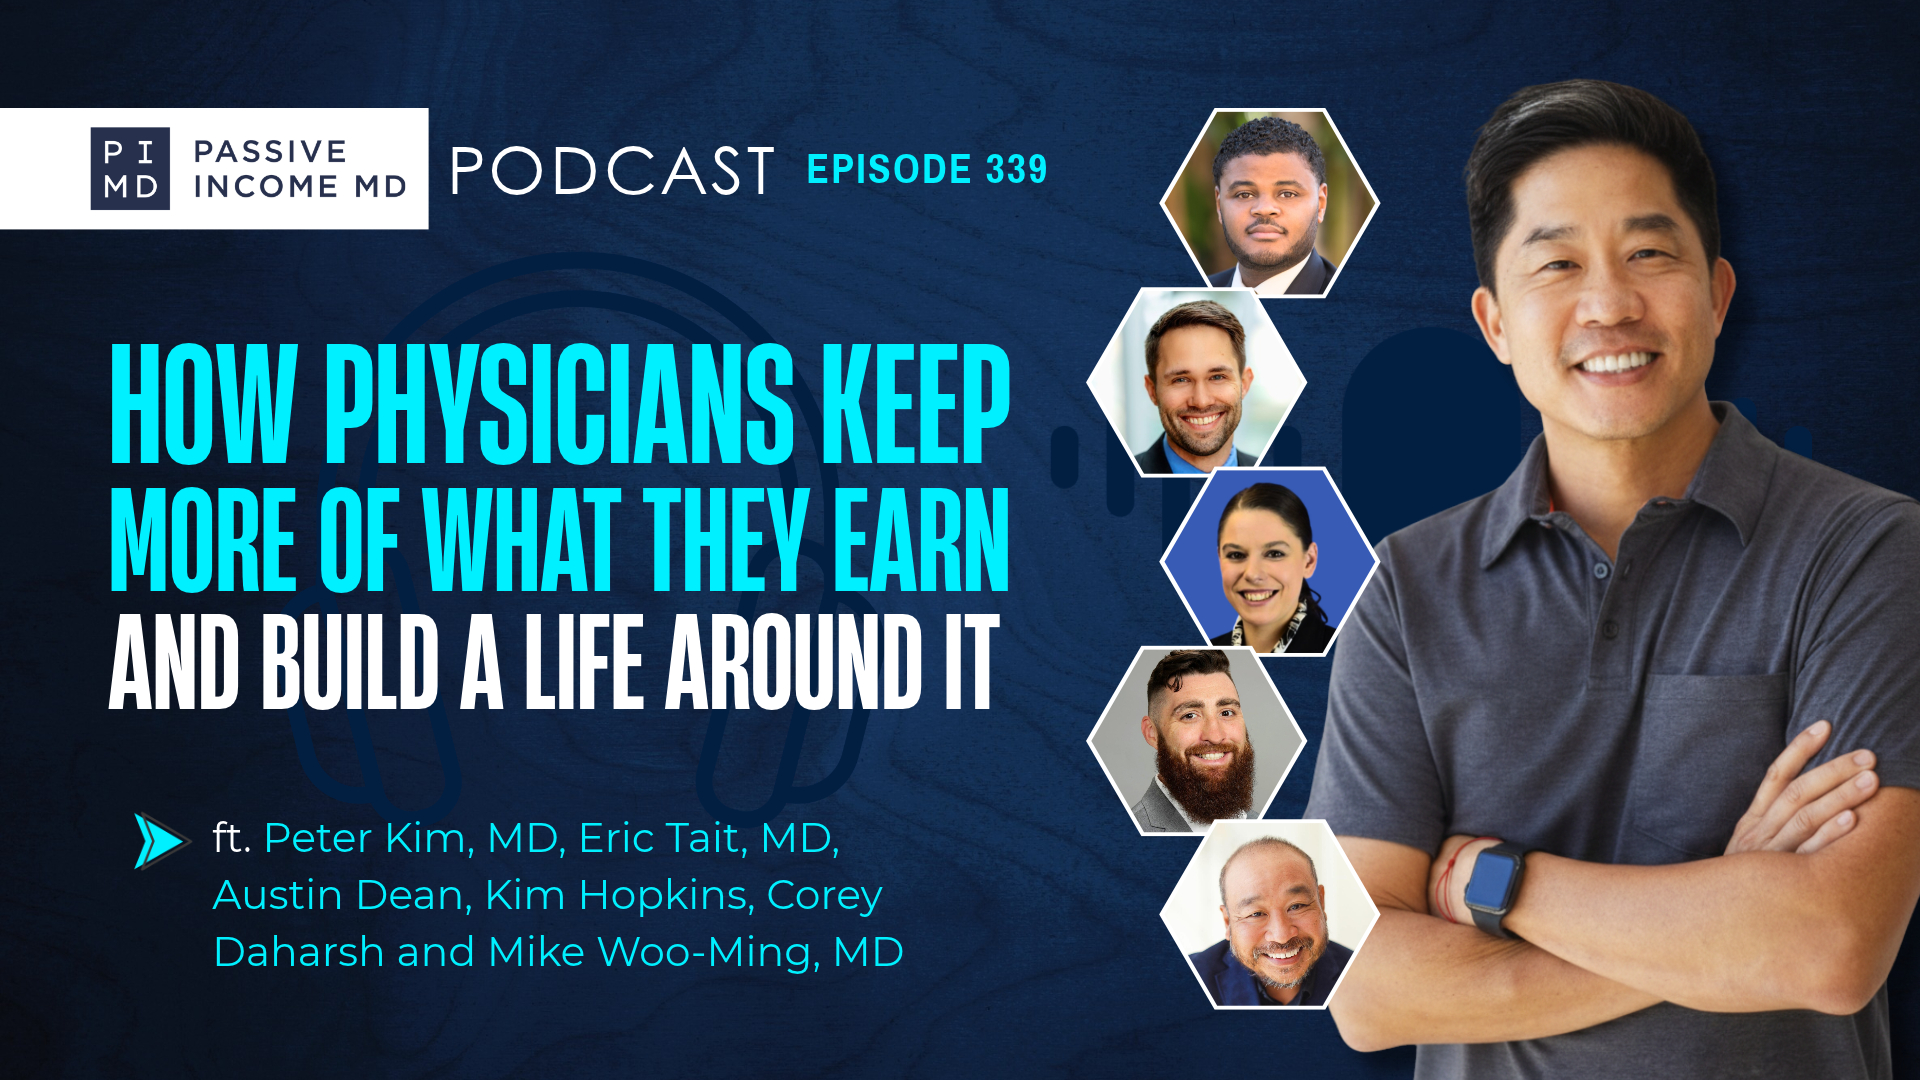
This episode is a panel from the third night of Encore Nights, the virtual sessions PIMD ran the week after PIMDCON. Peter says they’ll cover tax strategy that’s available to practicing physicians, how to use retirement accounts for more than index funds, and the bigger question underneath it all: what are you designing your life around, and does your money reflect that. He frames it for anyone who’s earning well but not building with intention.
He then introduces the panel. Dr. Eric Tait founded Vernonville Asset Management, which manages nearly $400 million across real estate and private equity, and he runs other businesses like an insulin infusion center. Austin Dean is the CEO and founder of Waystone Advisors, a certified financial planner who brings wealth strategies once reserved for the ultra wealthy to a wider audience. Kim Hopkins is the director of tax planning at Doc Wealth, a physician founded tax firm serving thousands of physicians in all 50 states. Corey Daharsh is a certified IRA service professional at Advanta IRA, and Dr. Mike Woo-Ming is a Mayo Clinic trained physician, multiple practice owner, lead coach at Momentum MD, and founder of Bootstrap MD.
What Alternatives Are, and Active vs Passive vs Debt
Peter starts by asking what wealth means to each panelist, and the answers keep circling back to time. Austin says wealth is having the flexibility to design life on your terms, and it doesn’t have to mean a ridiculous amount of money. It means being able to choose what’s most important, like leaving in the middle of the day to catch his son’s cross country meet. Eric says he always tells people wealth is measured in time, not money. Income is usually labor derived, so the question becomes how you put systems in place that pay you and let you live the life you want.
Mike echoes that and puts it in practical terms, asking who controls your calendar next week. If your income stops when you stop seeing patients, he says, what you have is a job, maybe a great and high paying one, but not wealth. He talks about using his MD as a platform for a podcast, a coaching business, and telemedicine, so no single income runs his life.
Kim and Corey add the other half of the picture. Kim says her clients want to keep what they’ve earned so they can reinvest it in tax advantaged investments or whatever makes them happy. Corey agrees that wealth is control of your own time and takes it a step further, saying established wealth can help you build a legacy and pursue passions outside of how you earn money, and that tax sheltered retirement accounts can work harder for you.
Finding Your Number and Making a Plan
Peter asks how physicians figure out what number is enough. Eric says most people think they need to replace their headline income, but what you really need to replace is your expenses. He suggests comparing your income per day to your expenses per day, then buying back days one at a time. Buy back four days and you’ve got a four day week, buy back eight and you’re working three days a week. Since many physicians don’t want to leave medicine, only to do it less intensively, he recommends starting by buying back a single day a week, which makes it feel believable and gives you the breathing room to think about what’s next.
Austin says to start with your vision for why you want time freedom, then figure out how much cash flow you need and not just a target number. He shares a client who said he wanted to get to $10 million, and when they asked why, it came down to the lifestyle he wanted to fund. Austin also suggests auditing where your money is going. Common wisdom pushes people to put everything into 401ks and pay down debt, and he says that can lock money up until 60. In his experience, putting money in places that are flexible and accessible can create financial independence earlier, sometimes in your 50s, 40s, or even 30s.
Peter then asks Mike why so many physicians don’t act on what they learn. Mike says you have to really want it, and that a raise from $400,000 to $450,000 probably won’t change your life. He shares that he wanted to go part time to be there for his young son, was told that wasn’t an option, and ended up quitting, which took about six months and cost him money to exit as a shareholder. What made it possible was that he’d already built assets. He points out that a rental clearing $2,000 a month is an asset, while a raise often comes with more expectations and shifts, and he says to design your life first and let your income revolve around it.
Tax Strategy You Can Still Use This Year
Peter notes how many people he heard say they pay way too much in taxes, and asks Kim where to start. Kim says there’s still time in the last quarter to implement tax strategies and make tax advantaged investments before year end. Her first step is to get with someone who understands physician nuances, like locums work, 1099s, and a large W-2 alongside 1099 income, since not all CPAs or accounting firms see that regularly. She says small strategies stack up, and if a planner saves you $20,000, their fee is likely lower than what you keep. She compares tax planning to an onion, with layers you peel back over time, and says by year three with a tax planner you should be saving at least five figures and hopefully six.
Peter picks up on the difference between a tax preparer and a tax strategist and asks how to tell which one you’re talking to. Kim says to look at whether they meet with you throughout the year. If a firm only quotes you for the tax return, bookkeeping, and payroll, they aren’t planning to help you implement strategies. A good package, she says, includes four or even six meetings a year, otherwise you’re just getting a bill in April. The firm doesn’t have to be physician specific, but it does need to plan with you.
Corey then explains what’s possible with retirement accounts that most physicians don’t know about. A self-directed retirement account lets you invest in things like rental property, real estate syndications, and oil and gas inside a tax sheltered account. He says there’s about $40 trillion in U.S. retirement accounts but only about 4 percent is self-directed, mostly because people don’t know it exists. He cautions that retirement accounts aren’t meant for immediate cash flow unless you’re over 59 and a half or have a Roth you can access, and he mentions that Roth conversions can add upside.
Favorite Strategies and What to Do Before Year End
Reinvention Without Leaving Medicine YOU KNOW ALL TOO WELL THAT ENTREPRENEURSHIP CAN BE A LONELY BUSINESS.
If you are looking for a private, invitation-only Mastermind designed for physicians and high-performing professionals who will settle for no less than fulfilling their visions of success while helping others do the same — Momentum MD is for you!
Filling our next cohort now, limited spots are available! APPLY now!